


Car Insurance for Hybrid Cars
Car Insurance for Hybrid Cars

Written by
Kervin Mathew
Edited by
Ellie Garran
Reviewed by
Adrian BennettCompare car insurance policies the easy way
Save time and effort by comparing a range of car insurance quotes with iSelect

- What are hybrid cars and how do they work?
- Do I need special car insurance for a hybrid?
- Does a hybrid cost more to insure?
- What should I consider when choosing car insurance for a hybrid?
- How can I try and save on car insurance for a hybrid?
- Frequently asked questions
- Power up your search for hybrid car insurance

Long story short
Hybrid cars run on a combination of electricity and traditional fossil fuels
Hybrids, including plug-in hybrids, made up 20% of all new vehicle sales as of December 2025.
You don’t need special hybrid car insurance, but pay attention to the level of cover
Comprehensive car insurance is the only type that will cover damage to your own car.
Car insurance for a hybrid vehicle can be more expensive
This is because they have higher repair costs due to their more advanced technology.
What are hybrid cars and how do they work?
Hybrid cars are vehicles that are powered by both an internal combustion engine that runs on traditional fossil fuels and an electric motor powered by electricity stored in onboard batteries. Depending on the technology they’re built around, hybrids can use either power source on its own or a combination of both. They generally come in non-plug-in (conventional) or plug-in varieties – the former uses technology such as regenerative braking to ‘self-charge’ its batteries, while the latter’s batteries are charged via an external source of electricity, such as a charging station or power outlet.
Known for their fuel efficiency and lower running costs, hybrids are gaining traction with road users Down Under, allowing motorists to experience the best of both worlds without having to pick a side.

Hybrid cars (excluding plug-in hybrids) clocked in at 199,133 sales in 2025, beating 2024’s 172,699. Along with plug-in hybrids, hybrid car sales made up more than 20% of Australia’s total new vehicle sales.
Currently, you might come across the following types of hybrids:
- Non-plug-in hybrid electric vehicle (HEV) – also known as a conventional hybrid, this runs on a petrol or diesel engine and an electric motor with ‘self-charging’ batteries, either one at a time or both at once.
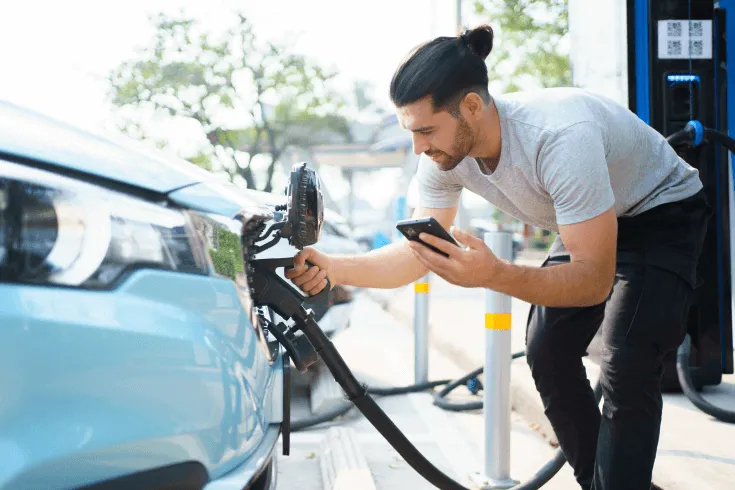
- Plug-in hybrid electric vehicle (PHEV) – this also runs on a petrol or diesel engine and an electric motor but has batteries that are charged by an external source like a power outlet or charging station.
- Mild-hybrid electric (MHEV) – this has a smaller electric motor and battery pack designed to make the main engine more fuel efficient, rather than power the car by itself.
The main difference between a hybrid and an electric vehicle (EV) is that EVs don’t have internal combustion engines and are powered solely by electricity.
Do I need special car insurance for a hybrid?
No, you don’t need a special type of car insurance to insure a hybrid. Any car insurance policy that covers a diesel or petrol vehicle can also cover a hybrid car – whether you’re after comprehensive car insurance, third-party property, fire and theft insurance or third-party property insurance.
Here are the types of car insurance you could consider for your hybrid.

Comprehensive car insurance is the only type of insurance that covers damage to your own car, regardless of who’s at fault. It also covers other people’s cars and property.

Third-party fire and theft insurance covers damage to other people’s cars and property, as well as theft and fire damage to your car.

Third-party property insurance covers damage you cause to other people’s cars and property, but it doesn’t cover damage to your own car.
Does a hybrid cost more to insure?
Yes, a hybrid car costs more to insure, mainly because of its relatively higher repair and replacement costs. Not only is a hybrid usually more expensive to purchase than its non-hybrid variant or equivalent, its parts and associated labour are also rarer to come by compared to most other vehicle types, contributing to a higher cost of repairs.
Here are some reasons why hybrids typically cost more to insure.
A hybrid vehicle can be more expensive to replace than a traditional car if it’s written off or stolen. And the higher the replacement cost, the higher the insurance premium.
The advanced gizmos and gadgets on a hybrid can sometimes be hard to repair or replace. There’s also a shortage of repairers specialising in hybrid vehicles.
Hybrid car batteries are a crucial part of any hybrid vehicle. And each of them can fall within a price range of $2,000 to $20,000 each. That’s a lot more than a traditional 12-volt car battery!
Bear in mind, there are a few other things that go into calculating your car insurance premiums:
- claims history and driving record
- age and gender
- where you park your car
- how much you drive
- your excess
- payment frequency (annually or monthly)
- level of cover, including optional extras.
So, if you’re looking to insure a hybrid car, you can expect higher-than-usual premiums. That’s why it always pays to compare policies to see which one strikes a good balance between budget and benefits. Don’t forget to check the Product Disclosure Statement for exclusions and conditions of cover as well.
 Helpful tip

After looking at car insurance pricing options, it might be easy to settle on a cheaper third-party policy. But if you factor in the costs of repairing or replacing a damaged hybrid vehicle, you might find that comprehensive cover is a no-brainer. Comprehensive car insurance policies can provide far more coverage and value, including exclusive options like agreed value cover, new car replacement and optional extras.
Adrian Bennett
General Manager for General Insurance
What should I consider when choosing car insurance for a hybrid?
Consider whether car insurance covers battery repairs and replacement, as well as charging equipment. Because hybrids need specialised repairers, you might also want to consider choice of repairer as an optional extra. Overall, think about the level of cover you want for your hybrid; whether you want cover only for accidental damage to other people’s cars and property or also for your own vehicle – in the latter case, you should be considering comprehensive car insurance.

Battery repairs and replacement
Because batteries do a lot of the work in hybrid cars, they can occasionally overheat and catch fire (aka thermal runaway). You might want your policy to cover battery damage, especially from fires.

Charging equipment
Plug-in hybrid electric vehicles (PHEVs) require charging cables or stations to recharge their batteries. If you have a PHEV, you might want to check your policy terms and whether or not it covers charging equipment such as loose cables.

Choice of repairer
Hybrid car technicians can be hard to find. Some policies can cover repairs done by your preferred hybrid car repairer, even if they’re outside the insurer’s repairer network.

New car replacement
Say your hybrid is written off or stolen. If your policy offers new car replacement, you can sleep easy knowing your car will be replaced with the same or a similar make and model.
How can I try and save on car insurance for a hybrid?
You can help lower your hybrid car’s insurance premium by reducing the risk you and your vehicle pose to the insurer – this could mean increasing your basic excess, knowing when to claim and even reducing your likelihood of making a claim. You could also compare and weigh up policies to see which one gives you a good balance of budget and benefits, like a low-kilometre comprehensive policy that rewards you with a lower premium if you don’t drive more than a specified kilometre-limit.
- Increase your excess – a higher excess typically reduces your premium because you take on more of the risk.
- Pay your premium annually instead of monthly or fortnightly to try and bag a discount from your insurer.
- Keep your car secure with anti-theft features and, if possible, in a lock-up garage or under cover.
- Limit the age and number of drivers listed on your policy. Younger drivers can up the risk factor.
- Consider a pay as you drive policy for reduced premiums if you drive within a certain kilometre-limit per year.
- Use a comparison tool to shop around for policies to help ensure you’re getting a good deal.
Frequently asked questions
Does car insurance cover charging equipment for hybrids?
Car insurance can cover the charging equipment within your car that’s essential for plug-in hybrids, depending on the insurer and the level of cover you choose. Bear in mind, you might need to declare or disclose charging accessories or equipment to the insurer for them to be covered.
Be sure to read the Product Disclosure Statement so you know whether or not a policy covers you for things like a damaged cable or charging station. In fact, something like a wall charger may be covered by a home insurance policy if it’s permanently fitted or wired to your home.
Does car insurance cover hybrid battery replacement?
Yes, car insurance can cover replacing your hybrid’s battery if it’s damaged due to an insured event such as a collision, storm, or fire or if it’s stolen. This is usually a benefit that comes with comprehensive car insurance. But anything outside of these events, such as battery replacement due to wear and tear, won’t be covered.
You can read the Product Disclosure Statement to get a better picture of what’s covered and not covered by car insurance.
How does car insurance for hybrids differ from electric vehicles (EVs)?
Hybrids are generally cheaper to insure than their slightly more advanced cousins, EVs, because their lower repair and replacement costs make them a lower risk to insurers.
More specifically:
- Hybrids use more conventional, less advanced components than EVs, making them cheaper to repair.
- Hybrids generally have a lower price tag than EVs, which is reflected in insurance premiums.
- Hybrids can have lower battery replacement costs because they require smaller battery systems than EVs.
- Unlike EVs, most hybrids don’t require external charging equipment (aka more stuff to insure).
Power up your search for hybrid car insurance
Before you charge in for a policy, give our comparison tool a go. It compares a range of policies from well-known car insurance brands in Australia for you. We can also help you sign up with one that works for you and your hybrid – all in a matter of minutes!
Get started on comparing car insurance policies!
Save time and effort by comparing a range of car insurance quotes with iSelect


iSelect General Pty Ltd (ABN 90 131 798 126. AFSL 334115) has partnered with Compare the Market (ABN 83 117 323 378. AFSL 422926) to compare a range of car insurers and policies. Not all providers in the market or all policies offered by the partners are compared and not all policies or special offers are available to all customers.
A number of our participating general insurance brands are arranged by Auto & General Services Pty Ltd ACN 003 617 909 on behalf of Auto & General Insurance Company Limited 111 586 353, both of which are related entities of iSelect Limited. Our relationship with those companies does not impact the integrity of our comparison service. Click here to view iSelect’s range of providers.
Any advice provided by iSelect is of a general nature and does not take into account your objectives, financial situation or needs. You need to consider the appropriateness of any information or general advice iSelect gives you, having regard to your personal situation, before acting on iSelect’s advice or purchasing any policy. You should consider iSelect’s Financial Services Guide which provides information about our services and your rights as a client of iSelect. iSelect receives commission for each policy sold that is a percentage of the premium or a flat fee. Ask us for more details before we provide you with any services.